SHRUTI CPA

Miro Acquisition: What Employees Should Know About Stock Options, RSUs and Taxes

If you work at Miro or still own equity from your time there, the acquisition announcement may have raised a more personal question than the headlines answer: What happens to my shares, and how much will I actually keep?

The answer depends on what you own, when you acquired it, and how your equity awards are treated in the transaction. Two employees receiving the same cash amount could have very different tax bills.

Here is what U.S. taxpayers should review before exercising options, signing an election, or spending an expected payout.

What Has Been Announced About the Miro Acquisition?

On September 10, 2026, Bending Spoons announced an agreement to acquire Miro in an all-cash transaction at a $1.355 billion enterprise value. Including Miro’s net cash, the announcement puts equity value at approximately $1.79 billion. Closing is expected in the fourth quarter of 2026, subject to approvals and other conditions.

Certain shareholders agreed to invest $295 million of their proceeds in Bending Spoons equity. However, this does not establish that every employee has a cash-versus-stock election. The public announcement does not disclose the payout or treatment of every employee equity award.

For employees, the key question is therefore not simply the headline acquisition price. It is how the transaction applies to your specific shares, options, RSUs, and other awards.

How Much Will My Miro Shares or Options Be Worth?

Do not simply multiply your ownership percentage by the headline purchase price and assume that is your payout.

You need to understand the consideration payable for your particular share class, applicable transaction adjustments, and the treatment of your individual equity awards.

If you hold options, your exercise price is also important. Ask the stock administrator for a written breakdown showing:

  • The transaction value per share applicable to your award
  •  Your eligible share or option count and exercise price
  • Whether the award will be paid out, assumed, replaced, or cancelled
  •  Any vesting conditions, deductions, holdbacks, or payment dates

An old funding valuation or 409A value is not a substitute for this information. Enterprise value and equity value are also different measurements.

Before making a tax decision, make sure you know, what you actually own and what the transaction documents say you will receive.

 Will My Miro Payout Be Wages or Capital Gains?

The tax treatment depends heavily on the type of equity you hold and what happens to it in the acquisition.

The following is general U.S. federal tax treatment and does not represent confirmed Miro award terms:

What to review for taxes when you have:

  1. Unexercised NSOs: Exercising generally creates compensation income on the spread. A cash payment for surrendering the option generally produces compensation rather than stock-sale capital gain.
  2. Previously exercised ISOs: The grant and exercise dates determine whether the sale meets the ISO holding periods. A sale may result in capital gain, ordinary income, or both.
  3. Unsettled RSUs: A taxable cash or stock settlement generally creates compensation income. Service vesting and settlement may occur on different dates.
  4. Shares already delivered through: A subsequent sale generally creates capital gain or loss based on the adjusted  RSUs or an NSO exercise tax basis rather than treating the entire proceeds as gain. 

These distinctions are important under IRS guidance concerning stock options, equity compensation, basis, and option dispositions.

An unexercised ISO that is cancelled for cash is also different from selling shares acquired through an ISO exercise. Simply seeing the label “ISO” on an original grant does not mean the transaction automatically receives qualifying-disposition treatment.

Should I Exercise My Miro Options Before Closing?

Not automatically.

Before exercising, confirm whether an exercise is permitted or necessary and compare the potential after-tax outcomes.

For favorable ISO qualifying-disposition treatment, a sale generally must occur more than two years after the grant date and more than one year after the exercise date. Exercising shortly before a cash acquisition does not automatically turn the resulting proceeds into long-term capital gain. If the required holding periods are not satisfied, some of the gain may instead be treated as ordinary income.

There are other considerations as well.

You may need substantial cash to exercise the options. The transaction could also be delayed. Therefore, an exercise decision should not be based solely on the assumption that the acquisition will close on its currently expected schedule.

A better approach is to model the potential outcomes under different scenarios before exercising.

What Happens to ISO AMT If the Deal Closes—or Is Delayed?

ISO exercises can create an alternative minimum tax, or AMT, issue.

If you exercise ISOs and continue holding the shares through year-end, the exercise may create an AMT adjustment even though you have not yet sold the shares.

If the shares are exercised and disposed of during the same calendar year, the IRS generally does not require a separate ISO exercise adjustment for AMT. However, that does not mean the transaction is tax-free or that AMT cannot arise for other reasons.

For an employee considering an exercise in 2026, it can be useful to model at least two scenarios:

1. The acquisition closes in 2026.
2. The acquisition is delayed until 2027.

The difference can be significant because the year-end ownership position may affect the AMT calculation.

If you paid AMT because of an earlier ISO exercise, gather your prior Forms 6251 and 8801. A minimum-tax credit may be available, but selling the shares does not automatically mean all prior AMT will be refunded. The amount of credit that can be used depends on your tax calculation.

What Happens to Unvested or Double-Trigger RSUs?

Do not assume that an acquisition automatically accelerates every RSU.

Your award documents and acquisition documents should be reviewed to determine whether your RSUs will:

  • Settle at closing
  • Continue vesting
  • Convert into replacement awards
  • Be cancelled or forfeited

If your RSUs have both a service condition and a liquidity condition, ask specifically how each condition will be treated.

For federal income-tax purposes, ordinary RSU arrangements generally result in compensation income when cash or vested shares are delivered. Deferred arrangements and employment-tax timing can require additional analysis. An RSU grant itself is not eligible for an 83(b) election.

Will Payroll Withhold Enough Tax?

Not necessarily.

For eligible supplemental wages, employers may use a flat, 22% federal income-tax withholding rate. The portion of annual supplemental wages above $1 million is generally subject to mandatory 37% withholding, subject to the applicable employer-aggregation rules. Employers may also use an aggregate method where permitted.

These are withholding rules not necessarily your final tax liability.

Your actual tax bill can be affected by:

  • Salary
  • Bonuses
  • Equity compensation
  • Your spouse’s income if filing jointly
  • Prior stock sales
  • Estimated tax payments
  • Federal and state taxes

Before spending a large acquisition-related payout, consider getting a tax projection that incorporates your full-year income.

Do I Need an Estimated Tax Payment Before the Acquisition Closes?

The acquisition announcement itself does not create taxable acquisition proceeds.

However, income you have already received during the year, including an earlier tender-offer payment, may create an estimated-tax obligation.

Federal estimated-tax penalty protection generally involves paying 90% of current-year tax or 100% of prior-year tax. The prior-year threshold can increase to 110% when prior-year AGI exceeds $150,000, or $75,000 for married taxpayers filing separately. The applicable rules and installment timing matter.

If income is concentrated late in the year, the annualized-income method may also be relevant rather than assuming income was earned evenly throughout the year.

California has an important additional consideration. For taxpayers with current-year California AGI of at least $1 million—or $500,000 for married/RDP taxpayers filing separately—the prior-year-tax safe harbor is unavailable, and the calculation generally must use 90% of current-year tax.

What If I Moved Out of California?

Moving out of California does not automatically eliminate California tax exposure related to equity compensation.

Compensation attributable to California services may remain California-source income after you leave the state. A separate stock-sale capital gain can follow different sourcing rules.

If you moved, keep records of:

  • Your move date
  • Where you worked
  • Work-location history
  • Grant dates
  • Vesting dates
  • Exercise dates
  • Award agreements
  • Sale dates

The appropriate allocation depends on the particular award and taxable event. One blanket allocation should not be applied to every form of equity compensation.

What If My Payout Is Lower Than Expected?

A lower valuation does not automatically create a deductible tax loss.

For shares that are sold, the starting point is generally the comparison between the sale proceeds and your adjusted tax basis.

Capital losses generally offset capital gains first. If you have a remaining net capital loss, up to $3,000 can generally offset other income each year, or $1,500 for married taxpayers filing separately. Unused losses can generally be carried forward.

This means a large stock loss may not immediately offset a large wage or equity-compensation payout dollar-for-dollar.

What Should Miro Employees Gather Now?

Before reviewing your potential tax exposure, gather the documents that establish what you own and how it was acquired.

At a minimum, consider collecting:

1. Your current equity statement and grant agreements, including amendments.
2. The acquisition FAQ and individual award-treatment notice once available.
3. Exercise confirmations, Forms 3921, and any filed 83(b) elections.
4. Prior RSU settlement, tender-offer, and stock-sale records.
5. Recent paystubs and federal and state estimated-tax payment confirmations.
6. Prior tax returns, AMT-credit schedules, and work-location history if you moved.

You should also ask HR separately about employment changes, retention arrangements, and any post-employment exercise deadlines.

This tax discussion does not assume that Miro has announced layoffs or that your employment will end.

Get Clarity Before Making an Equity Decision

The Miro acquisition may create an important tax-planning opportunity for employees and former employees who continue to hold equity.

At Shruti CPA, we help technology employees understand how equity decisions can affect their broader tax picture. A focused review can evaluate award treatment, exercise scenarios, potential AMT, withholding shortfalls, and state-tax exposure.

The goal is practical: understand what you may receive, determine how much you may need to reserve for taxes, and identify deadlines that require action.

Email us at hello@shruticpa.com to book a tax planning review.

FAQs

Does the Miro acquisition announcement itself trigger a tax bill?

No. The announcement alone does not create taxable acquisition proceeds. Tax timing depends on events such as an option exercise, RSU settlement, or completed share sale. Earlier exercises and sales need to be reviewed separately.

Can I calculate my payout from the announced acquisition price?

Not reliably. You should obtain your individual award-treatment statement and determine the transaction value applicable to your shares. For options, the exercise price, vesting terms, and transaction adjustments can also affect the amount you receive.

Should I exercise my Miro ISOs now to get capital-gains treatment?

Not without comparing the alternatives. An exercise shortly before closing may leave insufficient time to satisfy the ISO holding periods. Retaining exercised shares through year-end can also create AMT exposure. Confirm the exercise deadline and consider modeling a delayed closing.

Will all my unvested RSUs be paid at closing?

Do not assume so. Your grant agreement and acquisition documents determine whether awards accelerate, continue vesting, convert, or are cancelled. Ask the stock administrator to confirm your vesting and settlement treatment in writing.

Will I get back the AMT I paid on an earlier ISO exercise?

Possibly over time, but a sale does not automatically refund prior AMT. A minimum-tax credit may be available, and the amount that can be used in a particular year depends on your tax calculation.

If taxes are withheld from my payout, can I spend the rest?

First compare the withholding with your projected total tax liability. Payroll withholding is an advance payment and may not cover your final federal and state taxes. Your other income and estimated payments also affect how much you should reserve.

Can California still tax my equity if I have moved away?

Yes, potentially. Compensation attributable to California work may remain taxable in California after you move. Stock-sale capital gains can follow different sourcing rules, so your residency and work history should be reviewed separately for each award.

Can former Miro employees benefit from a tax review?

Yes. If you still hold Miro shares or outstanding awards, gather your equity statement, exercise records, prior tax returns, and transaction notices. You should also ask the stock administrator to confirm which holdings remain eligible and whether any action deadline applies.
Leveraged Foreign-Currency Deposits: What High-Income U.S. Taxpayers Need to Know

A leveraged foreign-currency deposit can look attractive on paper. A foreign bank may allow an investor to contribute a portion of the funds while borrowing the remainder, with the combined amount placed into a fixed foreign-currency deposit.

The advertised return, however, is only one part of the equation.

For high-income U.S. taxpayers, a leveraged foreign deposit(Foreign Currency Non Resident (FCNR) Deposits) can create significant federal and state tax considerations, investment-interest deduction limitations, Net Investment Income Tax exposure, and foreign-account reporting requirements. The tax treatment can substantially change the investment’s actual after-tax return.

Before investing, taxpayers should understand not only how the strategy works, but also how the income, loan interest, account balances, and reporting requirements may appear on a U.S. tax return.

What Is a Leveraged Foreign-Currency Deposit?

A typical leveraged foreign-currency deposit arrangement works like this:

  1. The investor contributes personal funds.
  2. The foreign bank provides a loan based on the investor’s contribution.
  3. The investor’s funds and the borrowed funds are combined and placed into a larger foreign-currency deposit.
  4. The deposit is pledged as collateral for the loan.
  5. At maturity, the deposit is used to repay the loan principal and interest.
  6. The investor keeps the remaining amount.

The potential economic return comes from the difference between the interest earned on the larger deposit and the interest charged on the borrowed funds.

For example, an investor might contribute $100,000 while the bank provides $900,000 of financing, creating a $1 million deposit. The investor’s potential return is therefore based on the larger deposit rather than solely on the investor’s original $100,000 contribution.

But leverage also magnifies the tax and reporting considerations.

Foreign Deposit Interest Is Generally Taxable in the U.S.

U.S. citizens and resident aliens are generally taxed on worldwide income. That means interest earned from a foreign bank deposit generally must be reported on a U.S. tax return.

This generally applies even if:

  • The foreign country does not tax the interest.
  • The foreign bank does not issue Form 1099-INT.
  • The interest remains inside the foreign account.
  • The deposit is denominated in U.S. dollars.

Foreign deposit interest is generally reported as interest income on Schedule B rather than simply reporting the net economic profit after subtracting the related loan interest.

For high-income taxpayers, the income may also be affected by:

  • Federal ordinary income tax.
  • The 3.8% Net Investment Income Tax.
  • State income tax.

California residents should pay particular attention because California generally taxes worldwide interest income earned by residents and does not provide a preferential rate for ordinary bank interest.

Can the Loan Interest Be Deducted?

Potentially—but the deduction is not automatic.

When borrowed funds are used to acquire an investment, the related interest may qualify as investment interest expense under Internal Revenue Code Section 163(d). The key issue is how the loan proceeds were actually used.

When the borrowed funds are directly deposited into the income-producing foreign deposit, the taxpayer may generally:

  1. Report the full foreign interest income on Schedule B.
  2. Calculate the allowable investment-interest deduction on Form 4952.
  3. Claim the allowable deduction as an itemized deduction on Schedule A.

California taxpayers may also need to consider California-specific reporting and deduction rules, including Form FTB 3526.

The investment-interest deduction is generally limited by the taxpayer’s net investment income. W-2 wages do not count as investment income for this limitation, and unused investment interest can generally be carried forward.

This means an investor should not assume that every dollar of loan interest will immediately reduce taxable income.

Why Loan Tracing Matters

One of the most important issues in a leveraged deposit arrangement is documenting exactly where the borrowed funds went.

The strongest documentation generally shows a direct movement of the loan proceeds into the designated investment deposit. The funds should not be routed through a personal checking account, mixed with ordinary savings or salary, or temporarily used for personal expenses.

Ideally, the transaction should clearly demonstrate:

Customer contribution + bank loan proceeds → designated foreign deposit

If the bank creates the loan and deposit through simultaneous internal entries, the taxpayer should consider requesting written confirmation that the loan proceeds were deposited directly into the identified foreign account and were not available for personal use.

Important records to retain include:

  • The executed loan agreement.
  • Deposit-opening confirmation.
  • Loan-disbursement records.
  • Documentation connecting the loan and deposit account numbers.
  • Evidence that the deposit is pledged as collateral.
  • Annual deposit-interest statements.
  • Annual loan-interest statements.
  • Records of the taxpayer’s personal contribution.

Ownership should also be consistent. If the loan is in one spouse’s name while the deposit is owned by the other spouse, additional analysis and documentation may be necessary.

Tax Timing Can Create a Cash-Flow Problem

Another important issue is when the income becomes taxable versus when the related loan interest becomes deductible.

Before investing, review the agreements carefully to determine:

  • When deposit interest is credited.
  • Whether interest is credited annually or only at maturity.
  • Whether credited interest can be withdrawn.
  • When loan interest is paid.
  • Whether loan interest is accrued, capitalized, or withheld at maturity.
  • What happens if the deposit is closed early.

A cash-basis taxpayer may face a particularly difficult situation if foreign deposit interest must be reported annually while the related loan interest is not treated as paid until maturity.

In that situation, the taxpayer could owe U.S. tax for several years without receiving the corresponding cash or being able to use the related interest deduction immediately.

This is why the investment should be evaluated based on annual after-tax cash flow, not simply the projected return over the entire investment period.

Foreign-Account Reporting: FBAR and Form 8938

A  leveraged foreign-currency deposit can also create significant information-reporting obligations.

Depending on the taxpayer’s circumstances, the account may need to be disclosed through:

  • Schedule B, Part III.
  • FinCEN Form 114, commonly known as the FBAR.
  • Form 8938, Statement of Specified Foreign Financial Assets.

These reporting requirements are separate. Filing Form 8938 does not replace the FBAR, and filing the FBAR does not replace Form 8938.

Does the Loan Reduce the Reportable Account Value?

Generally, no.

Foreign-account reporting can be based on the gross maximum value of the account, rather than the investor’s net equity after considering the associated loan.

For example, suppose:

  • Personal contribution: $100,000
  • Bank loan: $900,000
  • Foreign deposit: $1,000,000

The potentially reportable account value may be approximately $1 million, rather than only the investor’s $100,000 contribution.

Taxpayers should therefore maintain records of the maximum account value and the applicable exchange rates for each calendar year.

Estimated Taxes May Need to Be Adjusted

Foreign banks generally do not withhold U.S. income tax.

For a high-income taxpayer, the additional foreign interest income may therefore require adjustments to federal and state tax payments. Depending on the circumstances, the taxpayer may need to:

  • Increase payroll withholding.
  • Make quarterly estimated-tax payments.
  • Review federal and state estimated-tax safe harbors.
  • Include potential Net Investment Income Tax in the projection.

Waiting until the annual tax return is prepared can create an unexpectedly large balance due and potentially result in underpayment penalties.

What Should You Review Before Investing?

Before entering a leveraged foreign-currency deposit arrangement, obtain and review the complete documentation.

At a minimum, consider reviewing:

  1. The deposit agreement.
  2. The loan agreement and sanction letter.
  3. Deposit and loan compounding schedules.
  4. Written confirmation of fixed rates, if applicable.
  5. Interest-crediting and loan-payment provisions.
  6. Early-closure, default, and collateral provisions.
  7. Documentation showing how the loan proceeds were used.
  8. The identity and jurisdiction of the lending institution.
  9. Annual tax and account-reporting documents from the bank.
  10. A personalized federal and state tax projection.

Example: Why the Headline Yield May Be Misleading

Imagine a foreign bank promotes a leveraged deposit with an attractive headline yield.

An investor sees the potential interest earned on the full deposit and assumes the advertised rate represents the investment’s return.

But the actual result may be affected by:

  • Foreign deposit interest
  • Federal income tax
  •  3.8% Net Investment Income Tax, if applicable
  • State income tax
  • Loan interest
  • Potential investment-interest deduction limitations
  • Foreign-account compliance costs
  • Currency-related considerations
  • Timing of income and deductions

The result can be substantially different from the headline yield.

The correct question is therefore not:

“What interest rate does the bank advertise?”

Instead, ask:

“What is my projected after-tax compound return and annual cash flow after considering all U.S. tax consequences?”

FAQs

1. Is foreign fixed-deposit interest taxable in the United States?

Generally, yes. U.S. citizens and resident aliens generally report worldwide income, including interest earned from foreign fixed deposits. The interest may be taxable in the United States even if it is exempt from tax in the foreign country.

2. Is FCNR interest automatically tax-free for a U.S. taxpayer?

No. “Tax-free” treatment in another country does not automatically create a U.S. tax exemption. A U.S. taxpayer generally must consider the interest as part of worldwide income and may also have state tax obligations.

3. Where is foreign bank interest reported?

Foreign bank interest is generally reported as taxable interest on Schedule B. The income generally must be reported even when the foreign bank does not issue Form 1099-INT.

4.Can leveraged-deposit loan interest be deducted?

It may qualify as investment interest when the borrowed funds are properly traceable to an income-producing investment. The taxpayer generally uses Form 4952 to calculate the allowable deduction.

5. Can investment interest reduce W-2 income?

An allowable investment-interest deduction can reduce taxable income, but W-2 wages do not count as investment income for purposes of the investment-interest limitation. Sufficient qualifying investment income may be needed to use the deduction currently.

6. What happens if the investment-interest deduction is limited?

The unused amount can generally be carried forward. However, a carryforward does not eliminate the immediate cash-flow issue created when tax is due before the deduction can be fully used.

7.Does the 3.8% Net Investment Income Tax apply?

It may. Interest is generally included in net investment income, and high-income taxpayers may be subject to the 3.8% Net Investment Income Tax. Properly allocable investment-interest expense may affect the calculation, subject to the applicable rules.

📅 Book a consultation today to prepare for the 2026 tax year with confidence.

Real Estate Professional Status vs. Short-Term Rentals: A Tax Guide for Investors

For high-income real estate investors, particularly those earning significant W-2 income, two tax strategies often come up: Real Estate Professional Status (REPS) and the Short-Term Rental (STR) material-participation strategy.

While both strategies can potentially allow otherwise limited real estate losses to offset nonpassive income, they work under different parts of the passive activity loss rules.

Most importantly, you do not necessarily need to qualify as a real estate professional to potentially deduct a qualifying short-term rental loss against W-2 income.

REPS vs. Short-Term Rental Strategy

The biggest difference is how each strategy treats the activity under the passive activity rules.

REPS vs. Short-Term Rental Strategy

The biggest difference is how each strategy treats the activity under the passive activity rules.

 Real Estate Professional StatusShort-Term Rental Strategy
750-hour requirementYesNo
More than 50% of working time in real estateYesNo
Material participationRequiredGenerally required
Average guest stayGenerally not relevantRelevant
Spouse’s hours for 750-hour testNoN/A
Spouse’s hours for material participationYesYes

The federal rules generally treat rental activities as passive. REPS creates an exception for qualifying rental real estate, while certain short-term rentals may fall outside the definition of a rental activity altogether.

What Is Real Estate Professional Status?

For the tax year, the taxpayer generally must:

  1. Perform more than half of all personal services performed in trades or businesses in qualifying real-property trades or businesses in which the taxpayer materially participates.
  2. Perform more than 750 hours of services in those real-property trades or businesses.

Qualifying activities can include real estate development, construction, acquisition, rental and leasing, property management, and brokerage.

For full-time W-2 employees, REPS can be particularly difficult to satisfy because employee services generally do not count toward the REPS tests unless the taxpayer owns more than 5% of the employer.

Why This Matters for W-2 Employees

Consider someone who works approximately 2,000 hours for a technology company. Simply spending 751 hours managing rental properties does not automatically establish REPS because the taxpayer must also satisfy the more-than-half-of-personal-services test.

This is one reason the short-term rental strategy can be particularly relevant to high-income W-2 households.

How the Short-term Rental Strategy Works

A qualifying short-term rental may follow a different path.

Under the §469 regulations, an activity generally is not treated as a rental activity when the average period of customer use is seven days or less.

For example, suppose a property has:

  • 50 separate rentals
  • 250 total rental days

The average customer stay would be:

250 ÷ 50 = 5 days

Because the average is five days, the activity satisfies the seven-day-or-less test.

Importantly, this does not mean every guest must stay seven days or less. A few longer reservations do not necessarily disqualify the strategy because the calculation generally uses the average period of customer use for the year.

Seven Days Does Not Automatically Mean Schedule C

The seven-day rule is a passive-activity rule. It does not automatically determine whether the property should be reported on Schedule E or Schedule C or whether the income is subject to self-employment tax.

Those are separate tax questions.

Providing significant services to occupants, such as services comparable to hotel or maid services, can affect the reporting analysis.

Material Participation Still Matters

Meeting the seven-day average does not automatically make a short-term rental loss deductible against W-2 income.

The taxpayer generally must also materially participate in the activity for it to be treated as nonpassive.

The IRS provides seven material-participation tests. Three particularly relevant tests for short-term rental owners include:

More Than 500 Hours

You participate in the activity for more than 500 hours during the year.

Substantially All Participation

Your participation represents substantially all of the participation in the activity by everyone involved.

More Than 100 Hours and No One Participates More

You participate for more than 100 hours, and no other individual participates more than you.

This last test is important when a property manager or another worker is involved. Simply exceeding 100 hours is not enough if someone else participates more than you.

How Spousal Participation Works

Spousal participation is another area where REPS and the STR strategy are often confused.

For the 750-hour REPS requirement, spouses generally cannot combine their hours. One spouse must independently satisfy the REPS requirements.

However, the rule is different for material participation. A spouse’s participation can generally be counted when determining whether the taxpayer materially participates.

This distinction can be especially important for married couples who jointly manage a short-term rental.

When Can Real Estate Losses Offset W-2 Income?

There are several common scenarios.

Traditional Rental Without REPS

A traditional long-term rental is generally passive when the taxpayer does not qualify for REPS. Its losses generally cannot offset salary, bonuses, RSUs, or other nonpassive income.

There is a separate special rental real estate allowance for certain taxpayers who actively participate, but it phases out as income increases and may provide little or no current benefit to high-income W-2 households.

Traditional Rental With REPS

If a taxpayer satisfies the REPS requirements and materially participates in the rental activity, the rental may become nonpassive for federal purposes.

This can potentially allow otherwise allowable rental losses to offset nonpassive income such as wages.

Short-term Rental With Material Participation

A taxpayer may potentially use the STR strategy without qualifying for REPS.

For example, if the average customer stay is five days and the taxpayer satisfies a material-participation test, the activity may fall outside the rental-activity definition and be treated as a nonpassive trade or business activity.

In that situation, an allowable loss can potentially offset W-2 income federally without satisfying the 750-hour REPS requirement.

California Is Different

The california taxpayers need to pay particular attention to state treatment.

If california does not conform to IRC §469(c)(7), the federal real-estate-professional provision. As a result, a rental activity that is treated as nonpassive federally because the taxpayer qualifies for REPS may remain passive for California purposes.

The Short-term Rental analysis is different because the federal STR strategy can depend on whether the activity qualifies as a rental activity under the §469 regulations in the first place.

California generally follows the federal passive-activity framework subject to specified modifications, so the California treatment of a qualifying Short-term rental should be analyzed separately based on the property’s facts and the applicable state rules.

A Nonpassive Loss Is Not Necessarily an Unlimited Deduction

Even if you satisfy the REPS or short-term rental requirements, additional limitations may apply.

These can include:

  • Tax basis limitations
  • At-risk rules
  • Personal-use or vacation-home rules
  • Passive losses carried over from previous years
  • The §461(l) excess business loss limitation

For 2026 federal returns, the inflation-adjusted §461(l) threshold is $256,000, or $512,000 for married couples filing jointly.

Therefore, qualifying an activity as nonpassive does not automatically mean the entire loss can be deducted against W-2 income.

REPS vs. Short-term Rental: The Key Difference

A simple way to remember the distinction is:

REPS asks who you are and how much time you spend in real estate.

The Short-term Rental strategy first asks what kind of activity you have, including the average customer stay.

For a traditional rental, material participation alone generally does not eliminate the passive-loss limitation. Federal REPS may be necessary.

For a qualifying short-term rental with an average customer use of seven days or less, the activity may fall outside the rental-activity definition. If the taxpayer then materially participates, the 750-hour REPS requirement may not be necessary.

For California taxpayers, the analysis is even more important because California does not recognize the federal REPS exception under IRC §469(c)(7).

FAQs

1. Do I need REPS for a short-term rental?

Not necessarily. A qualifying short-term rental may potentially generate nonpassive losses if the taxpayer materially participates.

2. Is 100 hours enough for material participation?

Sometimes. One test requires more than 100 hours, with no other individual participating more than the taxpayer.

3. Can some guests stay longer than seven days?

Yes. Individual stays longer than seven days do not necessarily disqualify the strategy because the test generally considers the average customer-use period.

4. Can spouses combine hours for REPS?

Generally, no. Spouses cannot generally combine their hours to satisfy the 750-hour REPS requirement or the more-than-half-of-personal-services test. One spouse must independently satisfy the REPS requirements.

5. Can my spouse's hours count toward material participation?

Yes. For material participation purposes, a spouse’s participation can generally count toward the taxpayer’s participation in the activity.

6. Does California treat REPS the same way as federal law?

No. California does not conform to the federal REPS exception under IRC §469(c)(7). As a result, the federal and California treatment of the same real estate loss can differ.

7. Are nonpassive real estate losses always fully deductible?

No. Even when an activity is nonpassive, limitations such as basis, at-risk, personal-use, prior suspended losses, and excess business loss rules may restrict the deductible amount.

📅 Book a consultation today to prepare for the 2026 tax year with confidence.

Disclaimer: This guide is for informational purposes only and does not constitute legal or tax advice. Always consult a qualified tax professional for advice specific to your situation.

Divorce Tax Planning in California: What High-Income Professionals Should Know

Understanding Divorce Tax Planning in California

California divorce tax planning should be considered before a settlement is finalized. Different assets can have very different tax consequences even when they have similar market values. For example, a brokerage account with significant unrealized gains may have a different after-tax value than a retirement account or cash account of the same value.

Additionally, tax planning during divorce becomes especially important when a divorce involves real estate, investment accounts, retirement assets, business interests, or equity compensation. By considering the potential tax impact of each decision, you can evaluate settlement options based on their after-tax value rather than simply comparing their current market values.

1. Your Tax Filing Status After Divorce

Your marital status on December 31 determines your filing status for the entire tax year. Therefore, understanding your filing status is an important part of California divorce tax considerations.

Generally:

  • Married on December 31 – Married Filing Jointly or Married Filing Separately

  • Divorce finalized by December 31 – Single or Head of Household, if eligible

Choosing the correct filing status affects tax brackets, deductions, credits, and other tax considerations.

3. Selling the Family Home

For many couples, the family home is the largest asset. Consequently, the decision to sell, transfer, or retain the property can be an important part of tax planning during divorce.

Federal law may allow exclusion of gain on the sale of a principal residence if the applicable ownership and use requirements are satisfied. However, timing matters, and the rules can become more complicated after divorce.

4. RSUs, Stock Options, and Startup Equity

For California technology professionals, equity compensation is often one of the most valuable marital assets. As a result, California divorce tax planning can be particularly important when RSUs, stock options, or startup equity are involved.

Common issues include:

  • Restricted Stock Units (RSUs)

  • Incentive Stock Options (ISOs)

  • Nonqualified Stock Options (NSOs)

  • Employee Stock Purchase Plans (ESPPs)

  • Founder stock

  • Early exercised shares

  • Private company equity

Because equity compensation can involve ordinary income, capital gains, withholding, and potentially other tax considerations, individualized analysis may be necessary.

5. Retirement Accounts

Retirement assets are often divided during divorce. However, different account types can have different divorce tax considerations.

Common assets include:

  • 401(k)

  • Traditional IRA

  • Roth IRA

  • Pension plans

  • Deferred compensation

  • Executive retirement plans

Therefore, improper transfers should be avoided because they can create unnecessary taxes and penalties.

7. Business Owners

Divorce involving business interests presents additional challenges. In particular, divorce tax planning can help identify the potential tax consequences of transferring or buying out a business interest.

Important considerations include:

  • Basis

  • Buyouts

  • Asset versus equity transfers

  • Future distributions

  • Built-in gains

  • Depreciation

  • Pass-through income

  • Qualified Business Income (QBI) deduction

Moreover, business valuation and tax value are not always the same. Therefore, understanding the after-tax value of a business interest is critical during settlement negotiations.

8. Investment Accounts

Investment accounts often require detailed review. For instance, two accounts with identical market values may have dramatically different after-tax values depending on their embedded gains.

These California divorce tax considerations may include:

  • Cost basis

  • Unrealized capital gains

  • Tax-loss carryforwards

  • Concentrated stock positions

  • Restricted securities

  • Dividend income

  • Mutual funds

  • Exchange-traded funds

As a result, investment accounts should be evaluated based on both their current market value and potential future tax liability.

9. Estimated Taxes

Divorce can significantly change your income, withholding, and estimated tax requirements. Consequently, tax planning after divorce can help prevent unexpected tax bills or underpayment penalties.

Many newly divorced individuals discover that their previous withholding is no longer sufficient. Therefore, reviewing withholding and estimated tax payments should be part of the overall divorce tax planning process.

Divorce Tax Planning Checklist

Before your divorce is finalized, consider reviewing:

  • Filing status

  • Dependency planning

  • Child-related tax benefits

  • Equity compensation

  • RSUs

  • ISOs

  • NSOs

  • ESPPs

  • Startup equity

  • Business ownership

  • Home sale strategy

  • Rental properties

  • Retirement accounts

  • Investment basis

  • Capital gains

  • Estimated tax payments

  • Withholding

  • Trusts and beneficiaries

  • Estate planning documents

  • Cash-flow projections

  • Multi-year tax projections

A comprehensive divorce tax planning checklist can help ensure that important tax issues are considered before the settlement becomes final.

Why Tax Planning Before the Settlement Matters

Many settlement agreements focus on dividing assets equally by value. However, assets with the same market value may produce very different after-tax outcomes.

For example:

  • A brokerage account with substantial unrealized gains may be worth considerably less after taxes than a cash account of the same value.

  • Similarly, unvested equity awards may create future ordinary income and withholding obligations.

  • Meanwhile, retirement assets can have different tax consequences depending on account type and withdrawal timing.

Therefore, California divorce tax planning should evaluate the after-tax impact of proposed settlement options before an agreement is finalized.

Work With a Divorce Tax Planning CPA

Every divorce has unique tax consequences. For this reason, high-income professionals, startup employees, executives, business owners, and real estate investors often benefit from reviewing settlement proposals before they become final.

A proactive divorce tax planning in California review can help identify potential issues involving equity compensation, real estate, retirement accounts, estimated taxes, and long-term cash flow.

By addressing these issues early, you can better understand the potential after-tax impact of different decisions. Ultimately, professional California divorce tax planning can help you evaluate your options alongside your legal and financial objectives.

FAQs

1. How does divorce affect my tax filing status?

Your marital status on December 31 generally determines your federal filing status for that tax year. Depending on your circumstances, you may file as Single or potentially qualify for Head of Household.

2. Can divorce change how much tax I owe?

Yes. Divorce can change your filing status, income, deductions, credits, and other tax considerations. Your tax situation may be significantly different after the divorce.


3. Are RSUs and stock options taxable during divorce?

They can have tax consequences depending on the type of equity, vesting, exercise, and eventual sale. RSUs, ISOs, NSOs, ESPPs, and startup equity should be reviewed carefully before they are divided.

4. Should I consider taxes when dividing assets?

Yes. Two assets with the same current market value may have very different after-tax values. Unrealized gains, retirement accounts, and appreciated property can create different future tax liabilities.

5. Do retirement accounts require special tax planning during divorce?

Yes. Certain employer-sponsored retirement plans may require a Qualified Domestic Relations Order (QDRO) for a proper transfer. Incorrectly handling retirement assets can potentially result in unnecessary taxes or penalties.

6. Should I review my estate plan after divorce?

Yes. It can be important to review beneficiary designations, wills, trusts, life insurance, and other estate-planning documents after a divorce.

7. Is the tax treatment the same for every divorce?

No. Tax consequences depend on factors such as income, assets, investments, equity compensation, retirement accounts, business interests, and individual circumstances.

📅 Book a consultation today to prepare for the 2026 tax year with confidence.
Book A Free Call
Disclaimer: This guide is for informational purposes only and does not constitute legal or tax advice. Always consult a qualified tax professional for advice specific to your situation.
 

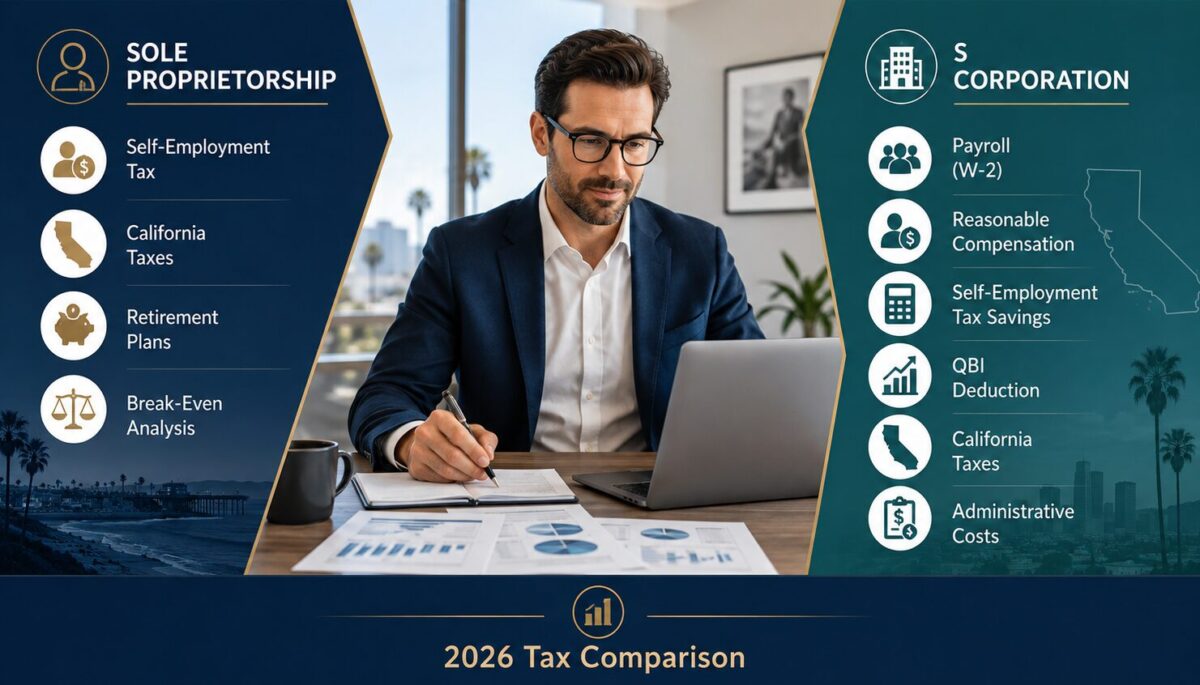
S Corp vs. Sole Proprietorship: Tax Guide for Consultants

Compare an S corporation vs sole proprietorship for consultants, including taxes, reasonable compensation, QBI, California taxes, retirement planning, and costs.

An S corporation may offer potential payroll-tax savings, but it also comes with additional requirements and expenses. A sole proprietorship is generally simpler to manage but may result in more income being subject to self-employment tax.

Here are the key factors consultants should consider before choosing a business structure.

Sole Proprietorship vs. S Corporation

Sole Proprietorship
A sole proprietor generally:

    • Has fewer administrative requirements
    • Reports business income on Schedule C
    • Pays self-employment tax on qualifying earnings
    • Does not receive a W-2 salary from the business

S Corporation
An S corporation generally requires the owner to:

    • Receive reasonable W-2 compensation

    • Run payroll

    • File additional tax returns

    • Maintain separate business records

    • Handle additional compliance requirements

Qualifying distributions generally aren’t subject to Social Security and Medicare payroll taxes, which can create potential tax savings.

Reasonable Compensation Matters

One of the most important considerations when comparing an S corporation vs sole proprietorship is reasonable compensation.
There is no required 50/50 or 60/40 salary-to-distribution rule. Compensation should reflect factors such as:

    • Work performed

    • Experience and responsibilities

    • Time spent working

    • Comparable market compensation

    • How the business generates revenue

For consultants whose income primarily comes from their personal expertise and services, an unusually low salary may be difficult to justify.

Tax Savings and the QBI Deduction
An S corporation may reduce certain payroll taxes, but the commonly quoted 15.3% savings does not apply to every dollar.

The Qualified Business Income (QBI) deduction can also affect the comparison. Consulting businesses may be classified as specified service trades or businesses (SSTBs), and S corporation W-2 compensation is not QBI.
As a result, potential payroll-tax savings should be evaluated together with the possible QBI impact.

California Tax Considerations

For California consultants, state taxes should also be included in the analysis.
California generally imposes a 1.5% tax on S corporation net income, with an $800 minimum tax generally applying.

Additional costs may include:

    • Payroll processing

    • Bookkeeping

    • Tax preparation

    • Corporate compliance

These expenses can reduce the overall benefit of an S corporation.

Don’t Forget Retirement Planning

Retirement planning can also influence the decision.
For an S corporation, retirement-plan contributions are generally based on W-2 compensation rather than distributions.

Therefore, while lower compensation may potentially reduce payroll taxes, it can also reduce retirement contribution capacity.
The right decision depends on factors such as:

    • Business profit

    • Reasonable compensation

    • Payroll-tax savings

    • QBI impact

    • California taxes

    • Retirement goals

    • Accounting and compliance costs

Key Takeaways

    • Run the numbers first: Compare potential tax savings with additional costs.

    • No fixed salary rule: There is no universal 50/50 or 60/40 requirement.

    • Reasonable compensation matters: Owners who work in the business generally need reasonable W-2 compensation.

    • Distributions aren’t tax-free: They may generally avoid payroll taxes when properly structured, but S corporation income remains subject to applicable income taxes.

    • California adds costs: Include state taxes and compliance expenses in your calculation.

    • Retirement planning matters: W-2 compensation can affect retirement-plan contribution capacity.

Choosing between an S corporation vs sole proprietorship should be based on your actual business numbers—not a simple income threshold.
Before making the switch, consider preparing a side-by-side projection of reasonable compensation, payroll taxes, QBI, California taxes, retirement contributions, and administrative costs.

The best business structure is the one that makes financial sense for your specific situation.

FAQs

1. What is the difference between an S corporation and a sole proprietorship?

A sole proprietorship is generally simpler and reports business income on Schedule C. An S corporation requires additional compliance, including payroll and reasonable W-2 compensation, but qualifying distributions may avoid Social Security and Medicare payroll taxes.

2. How much salary should an S corporation owner pay themselves?

There is no fixed 50/50 or 60/40 rule. Compensation should be reasonable based on the owner’s work, experience, responsibilities, time, comparable market pay, and how the business earns its income.

3.Does the QBI deduction affect the S corporation decision?

Yes. S corporation W-2 compensation is not QBI, and consulting businesses may be subject to SSTB limitations. The potential QBI impact should be included when comparing business structures.

4.Can an S corporation affect retirement contributions?

Yes. Retirement-plan contributions for an S corporation owner are generally based on W-2 compensation, not distributions. A lower salary may therefore affect retirement contribution potential.

5.Is there a specific income level where I should become an S corporation?

No. There is no universal income threshold. The decision should be based on a side-by-side projection using your actual business numbers.

6.Should I switch from a sole proprietorship to an S corporation?

Before making the change, consider preparing a tax projection that compares both structures. This can help determine whether the potential savings outweigh the additional taxes and costs.

7.Are S corporation distributions tax-free?

No. Qualifying distributions may generally avoid Social Security and Medicare payroll taxes, but S corporation income is generally still subject to applicable federal and state income taxes.

📅 Book a consultation today to prepare for the 2026 tax year with confidence.

Disclaimer: This guide is for informational purposes only and does not constitute legal or tax advice. Always consult a qualified tax professional for advice specific to your situation.